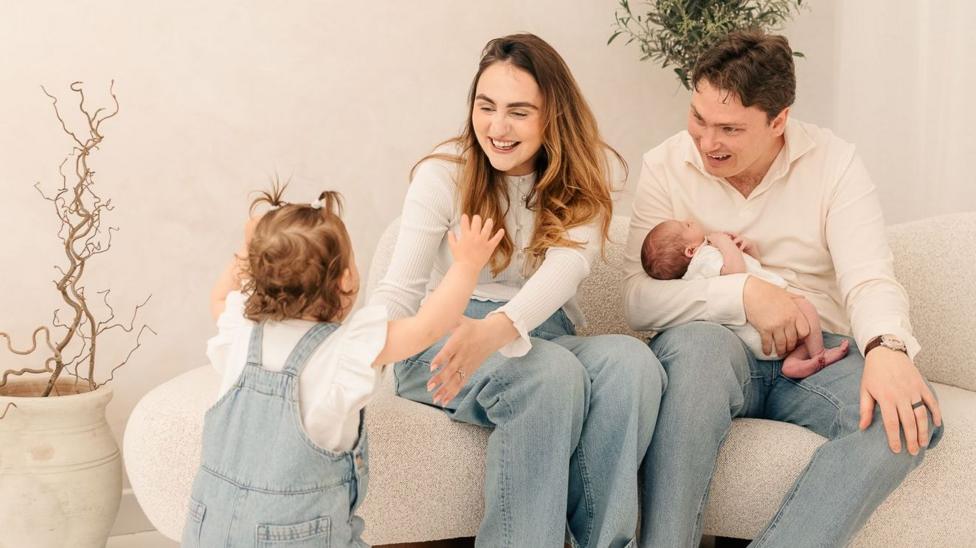
More parents are choosing to open retirement accounts for their children, opting for long-term investments that prioritize future financial security over immediate consumption. For Richard and Caitlin Brain from Swansea, Wales, this means contributing £50 monthly into pension funds for their children, aged 20 months and five months. Yet mum and dad have already set up pensions for them, richard and Caitlin Brain’s two children are aged just 20 months and five months respectively. The Brains, who live in Swansea, south Wales, are paying £50 a month into each of their kids’ accounts. Caitlin is currently on maternity leave from her job working for the local council. He earns less than £90,000 a year, while she currently doesn’t have an income as she has not yet returned to work after her statutory maternity pay of £194 a week ended. Starting a business or a house deposit, while the pensions are intended to provide financial security much later in life, the couple believe this is the best of both worlds â the ISAs could help their children with university costs.
Because of current UK private pension regulations, these funds remain inaccessible until the children reach age 57. This implies the oldest child will be unable to touch the money until 2082, while the youngest must wait until 2083. Despite the significant delay, Richard, 30, and Caitlin, 28, believe they are taking a prudent step. Richard, who works for an investment firm, notes that starting early allows money to grow for decades, enabling them to play a role in their children’s future long after they are gone. Despite the wait, Richard, 30, is convinced that he and Caitlin, 28, are doing the right thing.
Supporting these contributions requires lifestyle adjustments for the family. In addition to the £100 monthly total for pensions, they also invest £60 per child into Junior ISA savings accounts, which can be accessed at age 18 for expenses like university fees or housing deposits. Managing this total monthly outflow of £220, alongside their own savings and retirement contributions, necessitates living more frugally. The couple eats out less frequently than before and intentionally limits their spending on birthdays and Christmas to maintain their investment goals. We don’t eat out as often as we used to. In addition to £200 into their own private pensions and savings, the couple say they must live more frugally than in the past, paying a combined £220 a month into their kids’ funds.
Junior self-invested personal pensions, known as Junior SIPPs, have seen a surge in popularity since their 2001 introduction in the UK. Industry data highlights this trend: providers like Hargreaves Lansdown recorded two and a half times more account openings in the year leading up to April 2026 compared to the previous period. Fidelity reported that its account numbers have more than tripled since December 2023. Under current rules, parents can contribute up to £2,880 annually, with the government adding £720 in tax relief to reach a £3,600 total.
For some, the long wait is not a deterrent. Fifteen-year-old Hugo Thompson, whose parents have maximized his Junior SIPP contributions for a decade, views the investment as a strategic advantage. He expects the funds will help him retire earlier than the state pension age. His mother, Annabel, however, cautions that such accounts should only be considered once a family has achieved stability in their own financial and retirement planning.
Financial experts emphasize the power of compound interest in these early stages. According to Jemma Slingo, a pensions specialist at Fidelity, investing £50 a month from birth could result in a pot worth approximately £135,000 by retirement, based on an total contribution of £10,800 over 18 years.
The concept of early childhood investment is also gaining traction internationally. In the United States, an initiative known as Trump Accounts was introduced in July 2026. This scheme allows families, employers, and friends to contribute up to $5,000 (£3,800) annually per child. Unlike the UK’s rigid age-57 access rule, these accounts permit withdrawals starting at age 18, though they remain subject to taxes and a potential 10% penalty if withdrawn before age 59 and a half.
Wally Luckeydoo, a personal finance teacher in Tennessee, has utilized these accounts for his four and three-year-old children. Motivated by his own experiences—having lost his father early and witnessing his mother struggle with limited resources—he views these accounts as a way to alter his family’s financial trajectory. He emphasizes that he does not view this specifically as retirement savings, but rather as providing a necessary head start to overcome future financial burdens like student debt.