Global bond markets faced a frantic sell-off on Thursday, pushing 10-year US government borrowing costs to their highest point in 24 years. The yield on 10-year US Treasuries climbed to 5.34%, a level not seen since 2002, as traders braced for the potential of sustained high interest rates.
The pressure is being driven by mounting fears that US deficit levels are becoming unsustainable, alongside concerns regarding persistent inflation. In the United Kingdom, this international turmoil pushed the yield on 30-year gilts above 6% for the first time since 1998, placing additional strain on Chancellor John Healey ahead of his inaugural budget later this month. Yields for five- and 10-year UK bonds also saw significant increases.
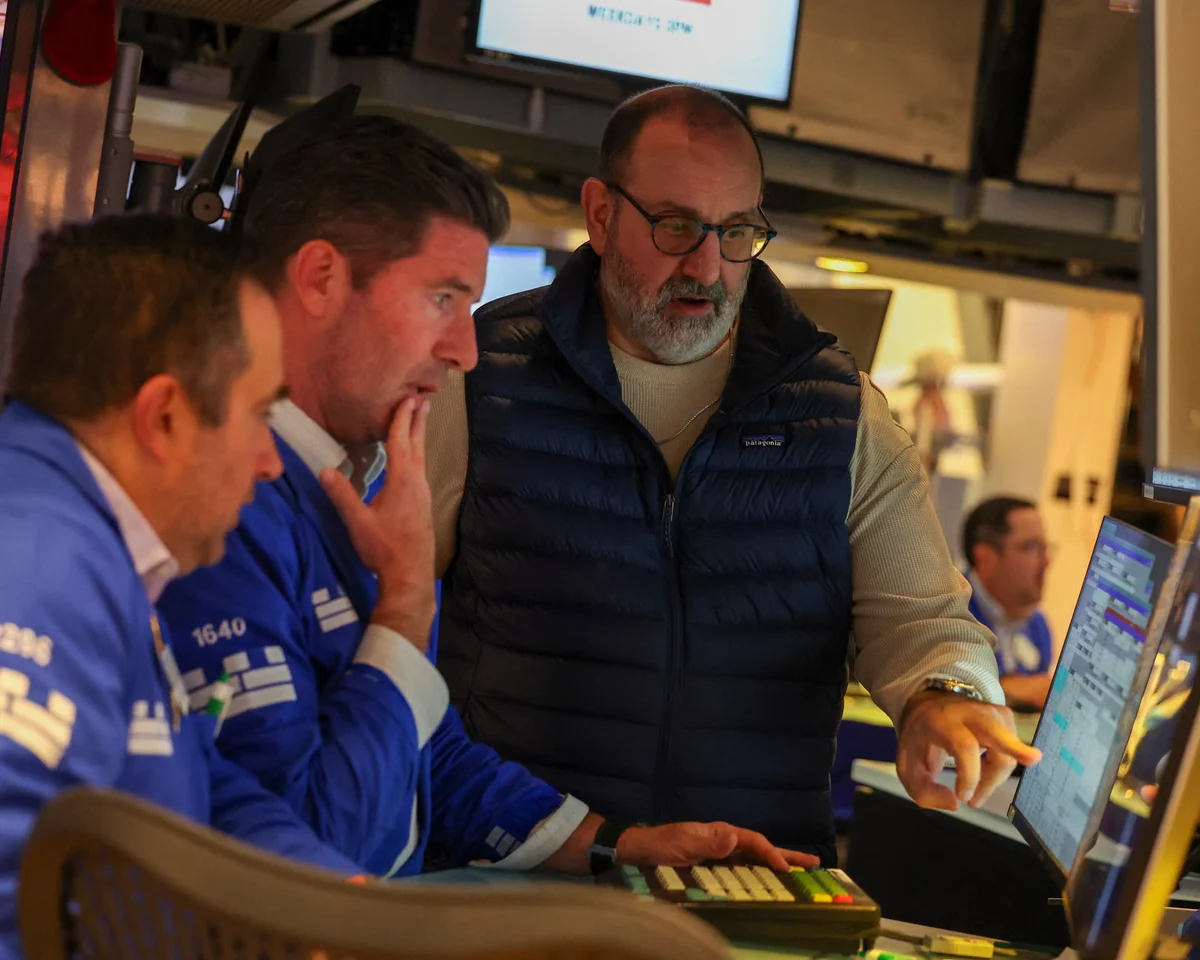
Stock markets responded sharply to the instability, with London’s FTSE 100 dropping nearly 1.7%, marking its worst daily performance since May. Similar declines hit European bourses, as Germany’s DAX fell 1% and France’s CAC 40 lost 1.6%. Neil Wilson, an investor strategist at Saxo UK, described the situation as “carnage” in the bond market, noting that the relentless rout is forcing investors to seek safer positions.
While recent US inflation data appeared slightly softer than anticipated, markets remained unimpressed. Investors are instead focused on the Federal Reserve’s ongoing battle against inflation, bolstered by a strong domestic economy and upward pressure on wages. Axel Rudolph, chief technical analyst at IG, noted that while some expectations for an October rate hike have receded, the risk of persistent inflation and rising oil prices could keep rates elevated, driving the dollar to a three-month high. With central banks expected to raise interest rates in the coming months to prevent price increases from becoming embedded, the threat of a renewed round of inflation from the persistently high cost of oil has spooked investors on both sides of the Atlantic. Mainly in response to the strength of the US economy and the prospect of workers bidding up their wages, traders remain anxious that the Fed will continue to raise interest rates to fight inflation.
Energy prices have further complicated the environment, with Brent crude rising 3% to approximately $101 per barrel. Although analysts suggest that exports from the strait of Hormuz have largely returned to pre-conflict levels through alternative transport routes, uncertainty regarding the long-term resolution of the Middle East conflict keeps prices volatile. Despite analysis that showed exports of crude from the strait of Hormuz have largely returned to levels seen before the outbreak of the Iran war, as oil producers and the shipping industry have found alternative ways of transporting crucial fuel out of the Middle East, oil prices rose again on Thursday.
Jefferies economist Mohit Kumar highlighted that bond markets are suffering from a lack of buyer appetite as investors demand more stability. He pointed to a combination of inflation fears, government deficit levels, and the volume of debt issuance as the primary weights on market sentiment. Hedge funds, currently nursing losses, have shown little interest in attempting to trade against the current downward trend. “There is also a buyers’ strike as investors do not want to step in till we get some form of stability.
The impact of this selling wave extended deep into the Eurozone. France saw its 10-year government bond yields reach 4.96%, the highest level since 2002. Furthermore, the spread between French and German yields has widened to a decade-long high, signaling increased market anxiety over the additional risk perceived in French sovereign debt. Japan’s 10-year yield similarly trended upward, approaching the 30-year peak established last month.