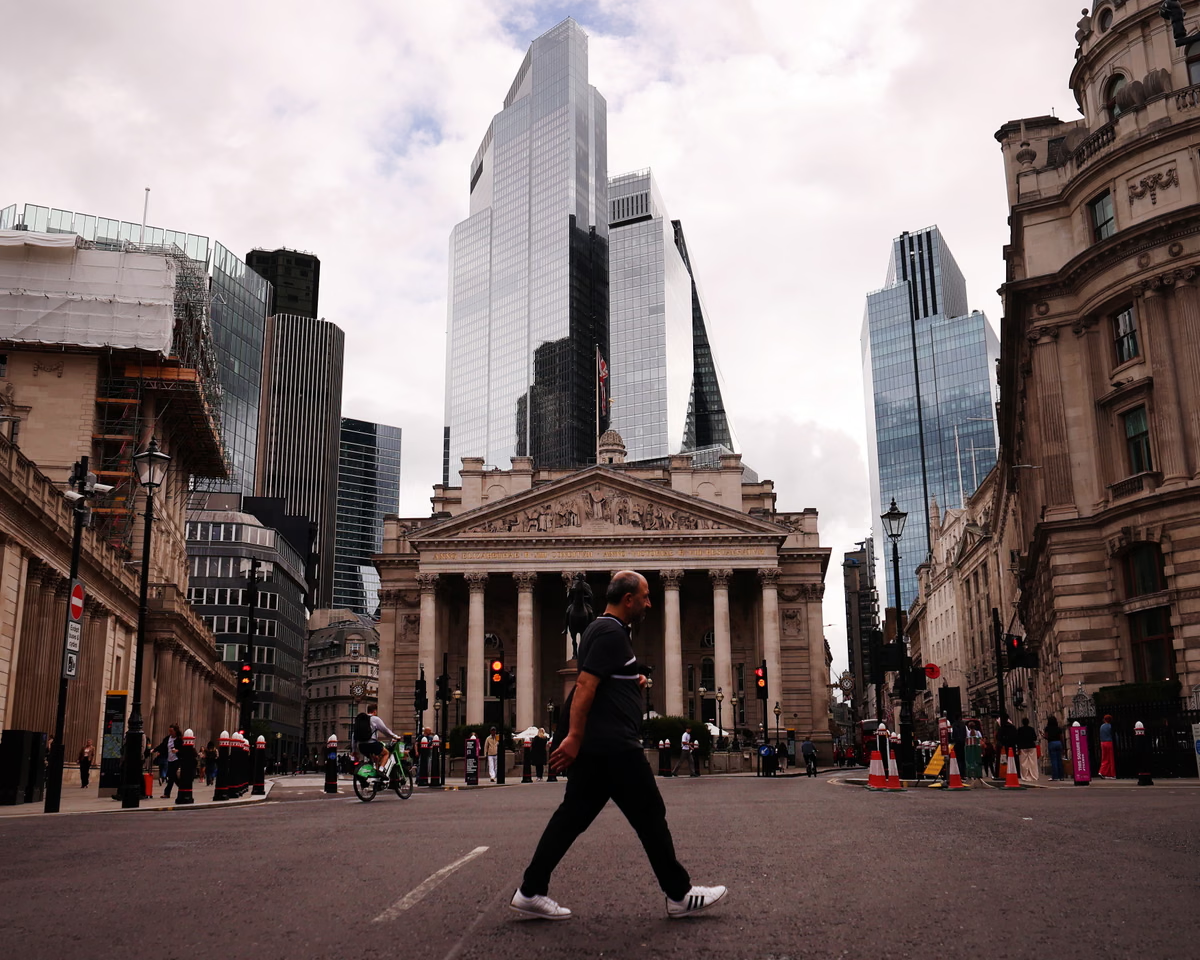
UK government borrowing costs surged to a 19-year high on Thursday as a global sell-off in bonds intensified. Investors are retreating from government debt amid heightening concerns over persistent inflation, placing significant strain on Chancellor John Healey just weeks before his maiden budget announcement on October 28. But will increase the pressure on John Healey ahead of his first budget as chancellor on 28 October, recent dramatic moves in government bond markets have been driven by international factors.
By midday in London, the interest rate on 10-year UK government bonds climbed 0.06 percentage points to reach 5.515%. This marks the highest yield recorded since July 2007, a period defined by the onset of the global financial crisis. Similarly, yields on 20-year and 30-year gilts have risen to their highest levels since 1998, reflecting the broader volatility currently impacting international bond markets.
Economic projections suggest that the combination of rising interest costs and a dampened growth outlook has effectively halved the £24bn fiscal buffer established by former Chancellor Rachel Reeves in March. With this safety margin eroding, expectations are mounting that Mr. Healey will use his upcoming budget to implement tax increases aimed at stabilizing the Treasury’s finances and funding specific initiatives, such as energy support for vulnerable households and a temporary VAT reduction on electricity. Economists believe rising borrowing costs and a weaker growth outlook are likely to have wiped out around half of the £24bn buffer against Labour’s fiscal rules that Healey’s predecessor, Rachel Reeves, built up at the time of her spring statement in March – perhaps significantly more. As well as paying for policy interventions including the six-month VAT cut on electricity bills and a modest energy support package for the poorest households, healey is expected to raise taxes at the budget to partly rebuild that cushion.
However, some financial analysts caution against aggressive fiscal tightening. Andrew Wishart of Berenberg Bank warned that prioritizing the maintenance of previous surplus targets through tax hikes could stifle economic incentives. Wishart suggested that gilt yields may eventually subside, noting that current market expectations for four Bank of England rate hikes may be overly pessimistic.
The Bank of England is widely expected to lift interest rates during its November session to combat inflation, aligning with restrictive monetary policies adopted by the Federal Reserve, the European Central Bank, and the Bank of Japan. This global trend toward higher rates is exacerbated by soaring oil prices linked to the ongoing conflict in the Middle East.
International Monetary Fund Managing Director Kristalina Georgieva has issued a stern call to global policymakers, urging them to act decisively. Speaking ahead of the IMF’s annual meeting in Bangkok, she emphasized that officials must utilize their available tools to address current economic pressures without further delay.
Beyond government balance sheets, these rising yields have tangible consequences for the wider economy, directly impacting borrowing costs for businesses and homeowners. Efforts by US Treasury Secretary Scott Bessent to mitigate yield spikes through expanded bond buybacks have so far struggled to stabilize the market. Since the doubling of buybacks was announced in August, yields on 30-year US Treasuries have climbed from roughly 5.235% to above 5.7%. While France has experienced particularly acute pressure during its own budget negotiations, the current market turbulence remains a widespread challenge for major economies.