A growing number of Generation Z and millennial employees are choosing to stop their workplace pension contributions, citing immediate financial strain caused by the rising cost of living. Government officials have warned that this trend could leave future retirees with significantly lower private pension income than those currently retiring.
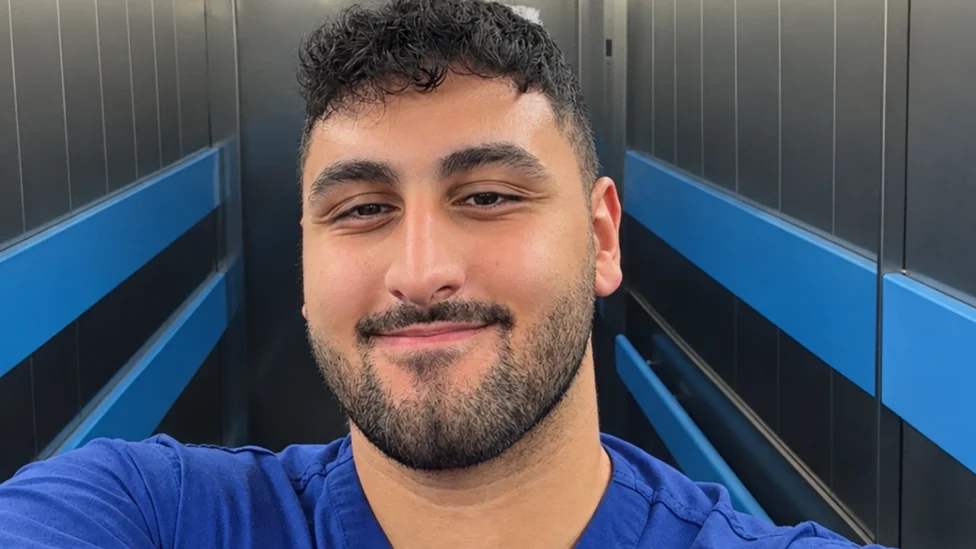
Hassan Nassar, a 26-year-old trainee GP in the West Midlands, recently paused his contributions to his NHS workplace pension. Until early September, he had been saving approximately £430 monthly. Nassar, who noted he was “really cash strapped,” plans to remain opted out for six to 12 months. He explained that he requires the capital to support a sick family member, manage rent and student loan payments, and save for a first home. He acknowledges the significant long-term cost of this decision, estimating a potential loss of £5,000 to £10,000 in future retirement income due to missed decades of compound interest. “People will say, you’re silly, look at what you’ll be missing out in the future,” he said. “But I need to look at what I’d be losing now if I didn’t opt out.” Despite these concerns, he remains determined to resume payments as soon as possible. Overall, however, he is confident he will have enough to retire on at the end of his “30-40” year career and is determined to opt back in to his pension as soon as he can. Share your tips with us on how you do it.Â.
The current system automatically enrolls employees aged 22 or older who earn over £10,000, though some exceptions apply. Typically, around 5% of a worker’s pay is deducted, supplemented by tax relief and a mandatory minimum employer contribution. While the NHS provides a substantial contribution on top of Nassar’s 10.7% monthly payment, it does not offer staff the flexibility to reduce contributions during financial hardship, unlike some private employers. According to hassan, He was paying 10.7% of his gross earnings each month into his workplace pension, while the NHS contributed a substantial amount on top.
Similar pressures are felt by younger workers like 22-year-old Evie from Cornwall. A recent drama school graduate now working at a London events company, she opted out of her workplace scheme because she struggled to cover basic outgoings, including food, transport, and £800 in monthly rent. Expressing the frustration felt by many, she questioned how she is expected to save for a home or a car while trying to survive daily expenses. “I don’t want to just work day in, day out to live, I want to work to have a life,” she added.
Department for Work and Pensions data indicates that while about 22.6 million people—roughly 90% of those eligible—are contributing to automatic enrollment pensions, approximately 2.5 million are not. Pensions Minister Torsten Bell noted that a rising number of young workers are choosing not to save, creating a danger that tomorrow’s retirees will face lower private income. Statistics show that in the three months to December, 11.5% of eligible 22 to 29-year-olds entering a new job opted out, up from 6.6% in 2020. Among 30 to 39-year-olds, the opt-out rate rose from 7.4% to 12.7%. That’s up from 6.6% in the same period of 2020.
Financial experts emphasize that stopping contributions carries heavy risks. April Leeson of The Private Office, a chartered financial advice firm, recommends that workers prioritize maintaining pension payments—even if at a reduced rate—to avoid losing out on employer contributions and the benefits of compounding. With the minimum pension age currently at 57, investments made in one’s 20s have at least three decades to grow. “£100 saved now, compounded at 4% a year over 30 years, is going to be worth a lot more than £100 saved in 15 to 20 years’ time,” she noted, urging younger workers to prioritize their future needs.
The impact of stopping contributions is also a concern for older workers. Kharlee, a 47-year-old teacher from South East London, paused her contributions twice in the last five years due to financial constraints and estimates she missed out on £5,000 in savings. Although her financial situation has improved, she is now self-employed and not part of a private scheme. “I would like to feel my pension is secure, and I don’t feel like that,” she said. “I worry I’m not going to be able to live comfortably at the age of retirement.”