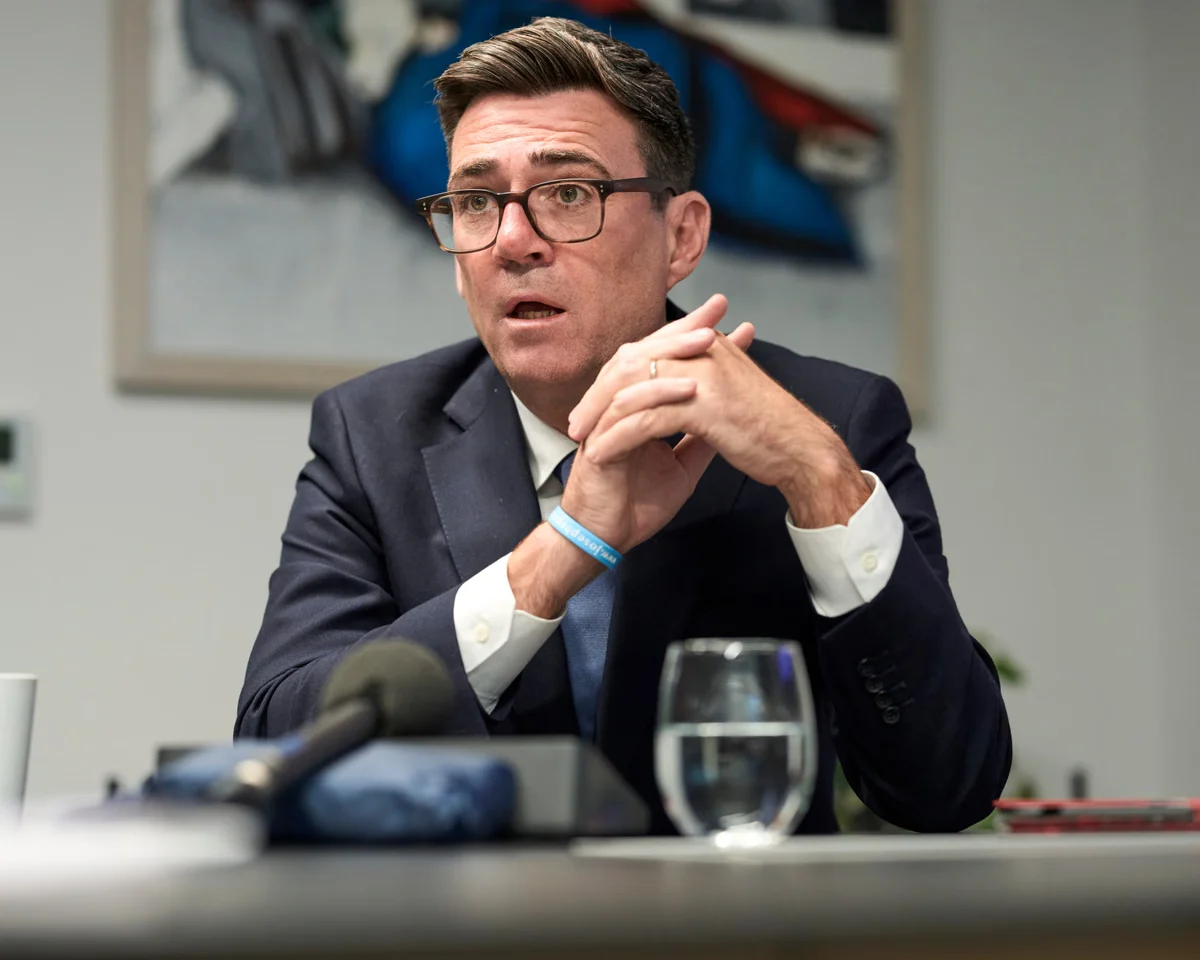
Prime Minister Andy Burnham has unveiled a significant housing policy, “Your first home,” designed to assist individuals in England who have a regular income but lack the savings for a substantial deposit or support from the “bank of mum and dad.” The program intends to provide first-time buyers with a 20% equity loan for the purchase of a new-build property, necessitating a minimum deposit of only 2.5% and featuring an initial interest-free window.
Speaking to the media ahead of the Labour Party conference in Liverpool, Burnham highlighted the struggle faced by young people who feel they have lost the chance to own a property. He stated that the new scheme will provide individuals with keys to their own front doors while simultaneously offering developers the confidence to supply high-quality housing. To ensure the support is directed at those truly in need, the government will implement household income and deposit caps, while property price limits will restrict the scheme to modest homes.
The initiative, which is set to be formally announced by John Healey during the upcoming budget, is scheduled to open for registration by the end of 2026. Officials confirmed that funding for the program will be derived from reprioritizing existing government budgets. Developers will be required to pay a fee linked to property values to help cover administrative costs. When questioned about concerns that increasing demand might inflate house prices, Burnham insisted the government remains committed to boosting housing supply across the board to maintain market stability. Or would mean cuts elsewhere, it was not immediately clear whether the money would come from funding already earmarked for housebuilding.
This policy arrives despite a noted lack of optimism from Housing Secretary Angela Rayner, who recently admitted there is only a “slim chance” of meeting the government’s target of constructing 1.5 million homes in England before the next election. While previous administrations, including those under Keir Starmer, explored similar concepts, earlier proposals were shelved by former Chancellor Rachel Reeves in favor of a stronger focus on supply.
The government is also moving to reclaim long-term vacant properties by updating empty dwelling management orders (Edmos). This shift allows local councils to gain control over more than 300,000 dwellings currently classified as “long-term empty” to provide shelter for families in need. The criteria for these orders will be tightened; the required vacancy period before a home becomes eligible for an Edmo will be slashed from two years to six months to prevent properties from falling into ruin. Reversing changes made by the Conservatives, burnham also unveiled plans to strengthen the powers of local leaders to take over long-term empty and derelict homes.
Furthermore, the administrative burden on local authorities will be reduced by lifting specific evidential requirements currently demanded by the residential property tribunal. By simplifying this process, the government aims to empower local officials to act with greater speed and decisiveness. These measures follow a lineage of similar government interventions, starting with the 2013 help-to-buy scheme introduced by George Osborne, which supported roughly one-fifth of first-time buyer purchases by 2014-15. Under which 387,000 people were supported, after concerns it was targeted at those who would have got on the housing ladder anyway and contributed to soaring house prices, some changes have been made to George Osborne’s original scheme. Both applied to homes worth up to £600,000, and by 2014-15, they supported about a fifth of first-time buyer purchases.
A subsequent iteration of the help-to-buy model in 2020 allowed for equity loans of up to 20% of a property’s value—or 40% within London—subject to regional price caps. A recent government review suggested these historical schemes provided significant value, estimating that they generated £25 billion of social value during the last financial year. Burnham noted that while the original programs were popular, adjustments were necessary to ensure the new version is strictly targeted at those who genuinely require financial assistance. He launched a second version, later that year.
Comments