Three major international organizations have issued serious warnings regarding surging borrowing expenses and mounting debt burdens across several large nations.
The Paris-based Organisation for Economic Co-operation and Development, the International Monetary Fund, and the International Institute of Finance pointed out the acute risks tied to high interest rates acting on $365tn in worldwide borrowing.
In its quarterly debt monitor, the IIF projected a structurally debt-intensive future driven by government and corporate investments in emerging technologies alongside demographic aging pressures.
The institution noted that global debt accumulation is accelerating as public and private entities compete to enhance growth amidst shifting economic structures.
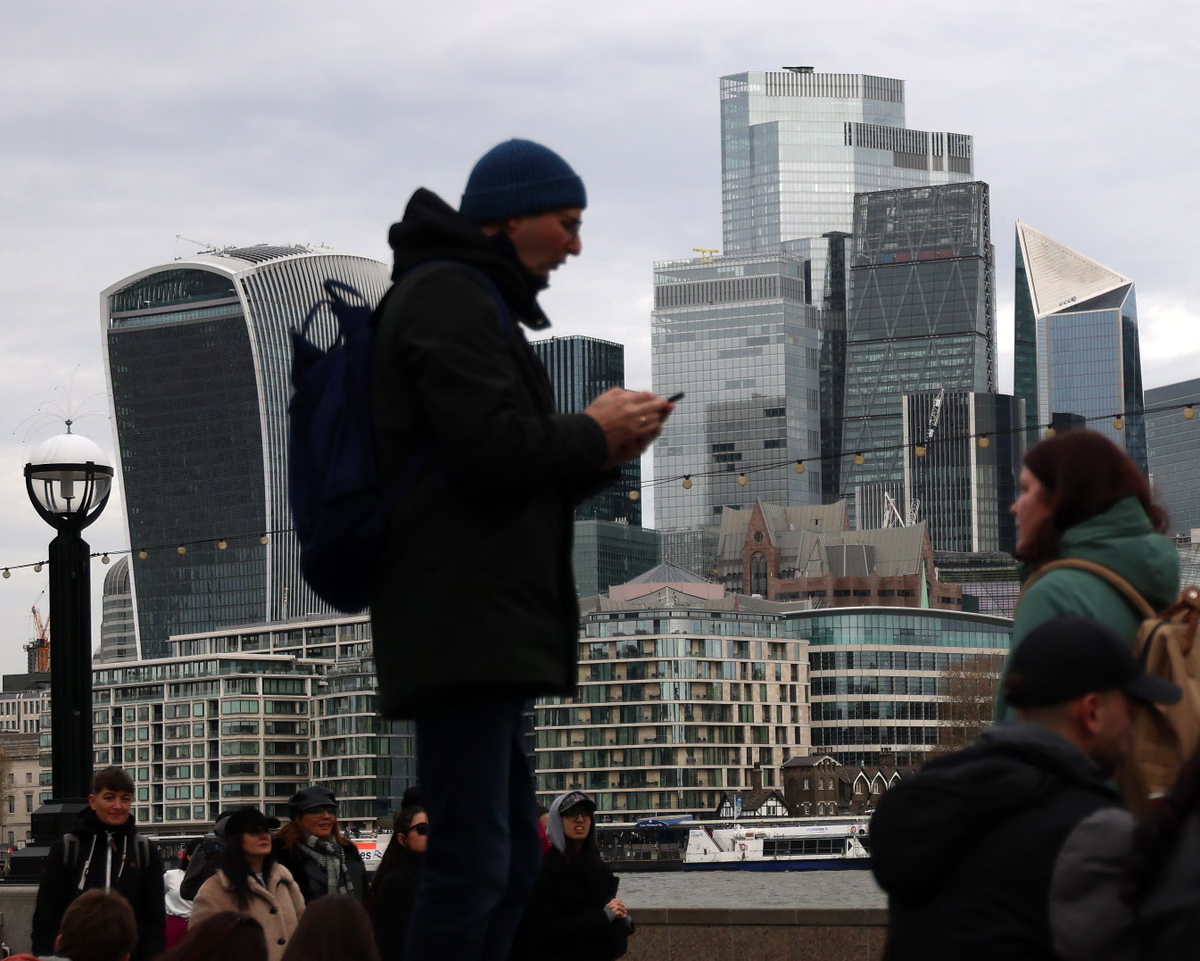
It explicitly compared prominent economies like the US, France, the UK, and Japan to emerging nations facing severe debt distress, citing persistently large deficits and mounting interest payments.
With upcoming elections discouraging politicians from implementing unpopular austerity measures, the group warned that existing unsustainable debt trajectories risk further deterioration.
Addressing reporters in New York during the UN general assembly, UK Prime Minister Andy Burnham disputed claims that he felt surprised by the condition of public finances upon taking office in July, noting that access talks provided clear foresight before Middle East developments altered the landscape.
Meanwhile, the OECD highlighted escalating government debt-servicing costs as a primary threat to worldwide economic stability in the near term.
Presenting the interim economic outlook, OECD Secretary General Mathias Cormann acknowledged that global growth displayed resilience despite pressures from the US-Israel conflict on Iran, but cautioned that fiscal and financial vulnerabilities have intensified.
Cormann pointed out that 30-year government bond yields across six G7 economies sit at 15-year highs or greater, driving up expenses for strained public budgets as well as households and businesses.
Those concerns reinforced earlier statements from IMF Managing Director Kristalina Georgieva, who urged advanced economies to tackle borrowing and reduce debt levels rather than allowing service costs to climb unchecked.
Georgieva stressed that political courage is necessary to reverse economic shocks that have continuously pushed obligations upward.
In its 9 percent—a modest 0.1 percentage point increase from June—while trimming next year’s outlook slightly from 3.1 percent to 3 percent.
The organization cautioned that prospects remain heavily reliant on achieving a lasting resolution to the Middle East conflict and maintaining stable energy markets.
Additionally, the OECD identified the record-breaking El Niño weather phenomenon as a significant downside risk capable of disrupting agricultural production and elevating food prices.
For the UK specifically, the OECD reduced its annual inflation forecast from 3.7 percent to 3.1 percent following softer-than-expected price increases, while upgrading economic growth forecasts for 2026 to 1.1 percent. The report also notes that “The buildup in global debt is set to accelerate as governments and corporates compete to boost growth and secure their positions in an economy reshaped by structural changes,” it said. The report also notes that and belt-tightening unlikely to be popular with voters, it said: “The risk is that already-unsustainable debt trajectories continue to deteriorate.”, with many politicians facing elections in the coming months. The report also notes that “It’s not the case that we were surprised when we came in, not least because I was in access talks and understood very clearly the position,” he told reporters. “The truth of the matter is that because of the situation i. The report also notes that including the UK, with crisis-hit emerging countries, it compared the current status of some of the world’s largest economies.
Comments