A growing number of prospective homeowners are navigating the property market without the traditional savings buffer, utilizing niche mortgage products that require little to no upfront deposit. Recent Bank of England data indicates that the proportion of UK mortgages with deposits under 10% of a property’s value has reached its highest level since 2008. While this trend mirrors the era leading up to the global financial crisis, industry experts highlight that current lending criteria are significantly more rigorous than those of the past.
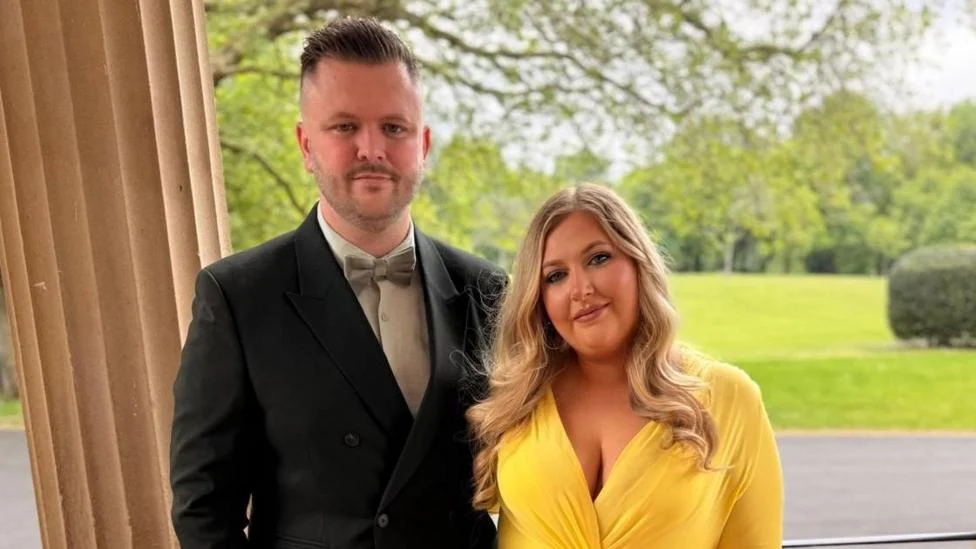
For Conroy, 32, and his partner Amber, 28, the prospect of property ownership seemed distant until they secured a Track Record mortgage from the Skipton Building Society. This product allows for 100% financing, meaning the borrower pays nothing upfront. By meeting strict eligibility requirements, including proof of consistent rental payments for 12 months and a solid credit history, the couple purchased a four-bedroom home in Swinton, near Manchester, for £242,000 in August. Their loan involves a 5.33% interest rate fixed for five years. Despite the higher cost, the couple noted that their £1,500 monthly payment aligns closely with their previous rent. Reflecting on the milestone, Conroy remarked, “I don’t think it’s dawned on us it’s really ours.”
Other lenders, including Lloyds, Santander, and the Yorkshire Building Society, have introduced products covering 95% to 100% of property values. These offerings aim to support buyers hampered by rising prices and the cost-of-living crisis. For instance, Bronya, 27, and George, 29, purchased a four-bedroom home in Rhuddlan, North Wales, in August using a Lloyds mortgage that required only a £5,000 deposit on a £258,000 purchase. With a 33-year term at a 5.89% fixed rate, they have committed to the property long-term, choosing to prioritize their savings for a £20,000 home renovation project rather than a larger initial deposit.
While these deals provide a path to homeownership for those with strong affordability but limited savings, they carry inherent risks. A primary concern is negative equity—a scenario where a property’s market value drops below the outstanding loan balance, which can lead to financial strain if the owner is forced to sell. Conroy noted that he plans to overpay his mortgage early on to build equity, acknowledging that entering the property market always involves an element of risk, though he remains optimistic about his area’s prospects.
Industry professionals, including David Hollingworth, associate director at L&C Mortgages, emphasize that lenders are now exercising greater caution. Modern affordability checks ensure that applicants have the means to manage higher rates, and some products, such as those from Lloyds, exclude new-builds or shared ownership homes to mitigate risk. Lenders are also demonstrating more flexibility in borrowing limits, provided the repayments are manageable.
Despite these safeguards, brokers advise potential buyers to approach low-deposit deals with prudence. Prospective homeowners are urged to carefully evaluate their monthly obligations and account for potential future interest rate hikes. As the market evolves, these mortgage options continue to serve as a vital, if scrutinized, gateway for first-time buyers attempting to climb onto the property ladder. The report also notes that they were renting in central Manchester where they work and could not afford to save up for a deposit. The report also notes that and some experts say riskier, type of mortgage that offered a solution, then they came across a relatively niche. The report also notes that the share of UK mortgages with deposits worth less than 10% of the property’s value is currently the highest it has been since 2008, external when such loans were widely available, according to the Bank of England. The report also notes that a solicitor, have a 25-year loan with monthly repayments of £1,500 – roughly what they were paying in rent, conroy and Amber. The report also notes that he says they feel comfortable with the higher cost because they “earn quite well” and expect their salaries to rise. The report also notes that we plan to stay here our whole lives.
Comments